While we are concerned about the effects of ratings linkage on regulated utilities, in no respect do we blame credit rating agencies. In fact, we strongly believe that the rating agencies are critical gatekeepers that point out for investors and regulators the potential linkages among holding company subsidiaries that could result in utility abuse or its credit downgrade.
A Better Measure for Profitability
A new way to measure what matters most: how close a unit comes to meeting its total potential profit.
Approximately 65 percent of capacity additions in the last few years have been gas-fired, combined-cycle units. Recent market conditions have been hard on these new resources, which have suffered from significantly low capacity factors. A better metric would measure a unit's ability to capture peak prices while minimizing shoulder period and off-peak losses. Furthermore, it would measure the extent to which a unit dispatches according to favorable market conditions.
Barriers to Entry: The Fight Against Power- Line Communications
And for a reasonable regulatory policy for new broadband technology.
To achieve the benefits of broadband over power line communications platforms, policy-makers must resolve a number of issues, including: (1) harmful radio interference; (2) access; and (3) cross-subsidies. If their policies impose diseconomies on the operation, design, or financial structure of BPL, widespread deployment of the technology is unlikely.
PJM/Midwest Market: Two Rival Groups Battle Over Grid Pricing
Should transmission owners get paid extra for distance and voltage?
While the Midwest now appears set on competitive bidding for the electricity commodity, taking from PJM such tried-and-true elements as locational marginal pricing, financial transmission rights, and a day-ahead market with a security-constrained dispatch, the region remains split over the pricing of transmission.
Changing Capital Structures for Changing Times
The utilities industry is in need of more equity.
Value Line projects that total capital for electric utilities will increase about 12 percent during the next several years, while common equity will increase nearly 28 percent. Similarly, natural gas distribution company total capital is projected to increase about 10 percent, and common equity close to 15 percent. For both industries, the median common equity ratio in the near-term future for companies with investment-grade rated subsidiaries is in the range of 51 to 52 percent. For utilities, higher equity ratios are desirable for several reasons.
Backed By Wind
The need for additional generation to compensate for wind variations is disappearing.
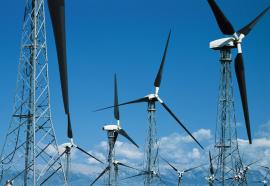
Utility-based studies have laid to rest the concern that a wind plant needs to be backed up with an equal amount of dispatchable generation. Even at moderate penetrations, ancillary services to back up new wind power need not be more than is required of a system as a whole.
Renewable Energy: Growing Pains, Halting Gains
Technology Corridor: Mandatory portfolio standards have different implications for different technologies.
The federal government and several state governments are considering programs to increase the share of electricity produced by renewable generation resources to 20 percent or more. If these programs are implemented and pursued successfully, they will trigger a dramatic change in the role of renewable generation and the requirements placed upon it by the market.
Regulatory Uncertainty: The Ratemaking Challenge Continues
In a joint survey conducted by Navigant Consulting and Public Utilities Fortnightly, utility executives identify the biggest challenge to their business.
A joint survey of utility executives by Navigant Consulting and Public Utilities Fortnightly identifies the biggest challenge regulators face.
Return on Equity: A Survey of Recent Rate Cases From State PUCs
Ratemaking Special Report
Our annual overview of ROE cases once again centers on interest rates, plus changes in the overall pattern of industry risk.
Transmission Upgrades: Who Pays?
How to allocate the costs.
An author examines the impact of hypothetical congestion-reduction projects on generators and loads that are part of a vertically integrated utility, and generators independently owned in a deregulated environment.